
Things to Consider When Purchasing a Lake Home
Buying a lake home can be a smart investment and a rewarding lifestyle choice. Whether you’re looking for a full-time residence, a vacation property, or a rental opportunity, waterfront homes come with unique factors that buyers should understand before making an offer.
Here are the key considerations to keep in mind.
Waterfront Location and Lake Type
Not all lakes are the same. Research whether the lake is natural or man-made, private or public, and how water levels are managed. Some reservoirs fluctuate seasonally, which can affect dock access and shoreline usability.
You should also check zoning regulations, short-term rental rules, and any homeowners’ association requirements. Properties on popular lakes near major cities often have stronger resale value, but they may also come with higher taxes and stricter guidelines.
Shoreline and Water Access
Evaluate the shoreline carefully. Is it rocky, sandy, or muddy? Is there a gradual slope into the water, or a steep drop-off? These factors affect swimming, boating, and long-term erosion risks.
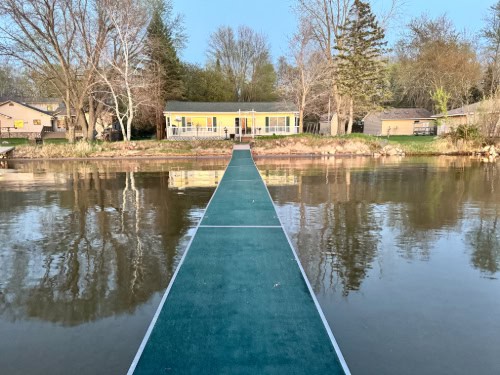
Look into dock permits and maintenance requirements. In some areas, dock installation is regulated by local or state agencies. Make sure the existing dock is compliant and in good structural condition.
Insurance and Financing
Lake homes may require additional insurance coverage. Flood insurance is often necessary, even if the property is not in a high-risk flood zone. Lenders may also have stricter requirements for waterfront properties, especially if the home will be used as a second residence or rental.
Before closing, get clear estimates for property taxes, insurance premiums, and utility costs.
Utilities and Infrastructure
Some lake homes are connected to municipal water and sewer systems, but others rely on wells and septic systems. Get these systems inspected before purchase. Rural lake properties may also have limited internet service or unpaved road access, which can affect daily convenience and resale value.
Maintenance and Ongoing Costs
Owning a lake home comes with additional maintenance responsibilities. Waterfront exposure increases wear and tear on siding, roofing, decks, and windows due to moisture and wind. Regular inspections and preventative maintenance are essential.
Shoreline management is another important factor. You may need to address erosion, maintain retaining walls, or manage vegetation along the water’s edge. Lake weed removal is often necessary to keep swimming areas and boat access clear. Depending on local regulations, this may require permits or professional services.
Docks, boat lifts, and seawalls also require seasonal maintenance. In colder climates, winterizing plumbing systems and removing docks before freezing conditions is critical to prevent damage.
Long-Term Value and Lifestyle Fit
Finally, think about how you plan to use the property. Is it easily accessible year-round? Are nearby amenities open during the off-season? Consider whether the home meets your long-term needs, not just summer recreation.
A lake home can offer strong lifestyle and investment benefits, but only if you understand the responsibilities that come with waterfront ownership. Taking time to evaluate location, regulations, and maintenance requirements will help you make a confident and informed decision.
ATR101126
 Advice for Buyers
How to Stop Paying Rent and Own Your Own Home
Are you tired of shelling out your hard-earned money every month to a landlord? It’s time to break free from the rent cycle and make the exciting transition to homeownership. Owning a home not only provides you with a sense of stability but also allows you to build equity and invest in your future. If you’re ready to take the leap towards owning your own home, here’s a step-by-step guide to help you on your journey:
1. Assess Your Financial Situation: Before embarking on the path to homeownership, it’s crucial to take a close look at your finances. Determine your current income, expenses, and savings. This will help you understand how much you can afford to spend on a home without straining your budget.
2. Establish a Savings Plan: Saving for a down payment is one of the most significant steps in the home-buying process. Aim to save at least 20% of the home’s purchase price as a down payment. This not only helps you secure a favorable mortgage rate but also reduces your monthly mortgage payments.
3. Check Your Credit Score: Your credit score plays a vital role in getting approved for a mortgage and securing a competitive interest rate. Review your credit report and address any issues that may be affecting your score. A higher credit score can save you thousands of dollars over the life of your mortgage.
4. Get Pre-Approved for a Mortgage: Getting pre-approved for a mortgage gives you a clear idea of how much you can borrow and the type of homes you can consider. It also signals to sellers that you’re a serious buyer, increasing your chances of a successful offer.
5. Define Your Needs and Wants: Create a list of your must-haves and nice-to-haves in a home. Consider factors like location, size, amenities, and proximity to schools and work. This list will help you narrow down your options and make the home search more manageable.
6. Engage a Real Estate Agent: Partnering with a skilled real estate agent who specializes in the local market can be a game-changer. They have access to valuable resources and insights that can help you find the right home at the right price.
7. Begin Your Home Search: With your agent’s guidance, start exploring homes that align with your preferences and budget. Attend open houses, schedule viewings, and don’t hesitate to ask questions about the properties you’re interested in.
8. Make an Informed Offer: When you find the perfect home, work with your real estate agent to make an informed and competitive offer. They’ll assist in negotiating terms that work in your favor while respecting the seller’s interests.
9. Conduct Inspections: Once your offer is accepted, schedule a professional home inspection. This step ensures that there are no hidden issues with the property that could turn into costly repairs down the line.
10. Closing the Deal: After successfully navigating the negotiation and inspection process, you’ll move on to closing the deal. This involves finalizing your mortgage, signing the necessary paperwork, and transferring ownership.
11. Celebrate Homeownership: Congratulations, you’re now a homeowner! This achievement marks the beginning of an exciting journey filled with memories and the potential for long-term financial stability.
Owning your own home is a milestone that brings a sense of pride and accomplishment. By following these steps and working with experienced professionals, you can bid farewell to rent payments and embrace the joys of homeownership.